• The earlier investment thesis has gained credibility: the ASOM full ownership benefit has arrived, margins have recovered, and West Africa work has progressed from expectation to orders and execution. |
Excerpts from UOB Kay Hian report
Analyst: Tang Kai Jie
3Q26: Higher Offshore Activities Drive Robust Growth
• 9M26 revenue of S$84.3m and PATMI of S$7.8m met 77.3% and 76.6% of our 2026 forecasts respectively, slightly ahead of expectations.
• 3Q26 gross margin recovered and jumped to 38.1%, while S$71.2m of remaining contracted work supports revenue visibility beyond 2026. |
|||||
Analysis
| Offshore execution restores margins. |
3Q26 revenue rose 10.1% yoy to S$28.6m and PATMI surged 174.6% to S$4.2m, meeting 26.2% and 41.8% of our 2026 forecasts respectively.
West Africa Basin execution and later stage Batam deliveries, alongside higher operational efficiencies, lifted 3Q26 gross profit 16.0% to S$10.9m and 3Q26 PBT 15.1% to S$5.2m, while 3Q26 EBITDA margin excluding other gains and losses reached 22.8% (3Q25: 18.2%).
9M26 revenue and PATMI grew 9.8% and 73.9% yoy to S$84.3m and S$7.8m respectively, meeting 77.3% and 76.6% of our full-year forecasts, slightly ahead of expectations.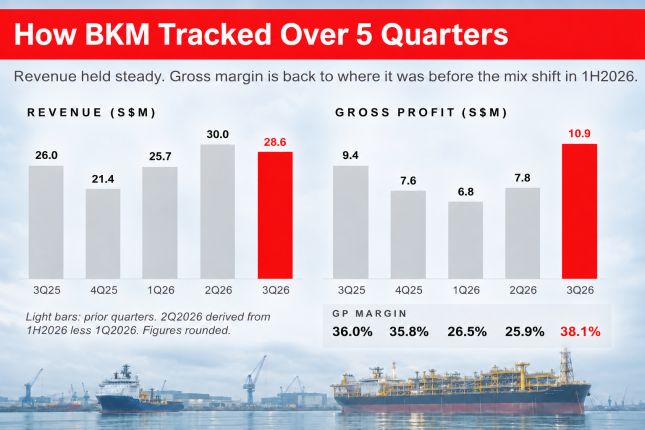
• Full ASOM ownership boosts earnings attribution. 3Q26 was the first full quarter of 100% ownership following the May acquisition of the remaining 49%.
Non-controlling interests fell to S$0.04m from S$1.51m in 3Q25, helping PATMI outpace PBT growth.
We expect 3Q26 results to be a good baseline to annualise Beng Kuang Marine’s (BKM) full-year result for 2027.
2027 will be the first full year of full ASOM earnings ownership.
| Infrastructure engineering drives growth |
In 3Q26, external infrastructure engineering (IE) revenue rose 18.4% yoy to S$24.8m, supported by offshore activity, barges and cranes. Segment profit rose 17.2% to S$6.2m, while group gross profit less administrative expenses rose 46.0% to S$5.6m.
Management reported positive contributions from Batam shipbuilding and cranes as execution progressed.
• Corrosion prevention prioritises cash discipline. In 3Q26, external corrosion prevention (CP) revenue fell 24.0% yoy to S$3.9m and segment PBT declined to S$0.5m.
Management deliberately reduced Indonesian exposure amid prolonged collections and currency weakness, while Singapore yard consolidation adds pressure. Productivity and S$2.5m of intercompany work, eliminated on consolidation, support utilisation.
| Recurring orders support visibility |
| The company indicated that around 80% of revenue is typically recurring, supported by repeat FPSO servicing and maintenance work, with higher-value life-extension projects providing additional upside. ASOM secured S$112.4m of work in 9M26, leaving S$59.8m outstanding at end-Sep 26, up S$7.5m from Jun 26. Some work extends beyond 2026, supporting revenue visibility into 2027. |
• Adjacent businesses add to delivery. BKM’s other core operating subsidiaries, PT. Nexus Engineering Indonesia (NEI) and International Offshore Equipments (IOE), had S$3.9m and S$7.5m of work remaining respectively, taking the combined balance with ASOM to S$71.2m.
Management reported positive contributions from Batam shipbuilding and cranes, while highlighting delivery schedules, logistics and cost control as priorities.
• Cash conversion and debt reduction remain priorities. Contract assets fell S$4.3m in 3Q26 as certification and billing advanced. Management reported improved operating cash flow and intends to use liquidity to reduce acquisition-related borrowings in 2027.
Converting certified billings into cash remains key to funding this repayment.
• Outlook supported by offshore execution. Management expects stronger execution to support 4Q26 and 2027 as life-extension work progresses, aided by accommodation capacity mobilised in September.
It is pursuing 1- 2 additional FPSO engagements and exploring other basins and asset types, creating opportunities for follow-on work.
Management cautioned that 3Q gross margin was already high, with further efficiency gains sought through integration and cost control.
|

 See also: BENG KUANG MARINE: From Crisis to Comeback: Ex-banker joins as CEO and turns company around hard |


