Like Phillips and KGI, OCBC places much of its emphasis on Wafermine, a ketamine wafer that dissolves under the tongue.
|
Excerpts from OCBC report
Analyst: Troy Cheng
• The USD41m US Department of Defense (DoD) contract funds Wafermine's Phase 3 and Emergency Use Authorisation (EUA) work without dilution
• An EUA would provide an early regulatory and manufacturing proof-point, ahead of Phase 3 data that we see as the main value catalyst |
|||||
Investment summary
| DoD funding converts Wafermine from an unfunded to a funded programme |
On 12 Feb 2026, iX announced a USD41m Other Transaction Agreement with the Defense Health Agency Contracting Activity (DHACA), awarded on a sole-source basis for a 36-month period of performance, to fund Phase 3 development and the activities required for a US Food and Drug Administration (FDA) EUA for DoD use.
The significance lies less in the amount than in who carries the risk.
Before the award, iX held SGD0.9m of cash in FY25 and would likely have needed repeated dilutive raises to fund a Phase 3 programme of this scale.
The programme is now externally funded, and iX retains the commercial rights.
The contract also flows through the income statement. FY26 revenue included SGD1.2m of development services linked to the programme. The contract should likely give revenue visibility over the next two years.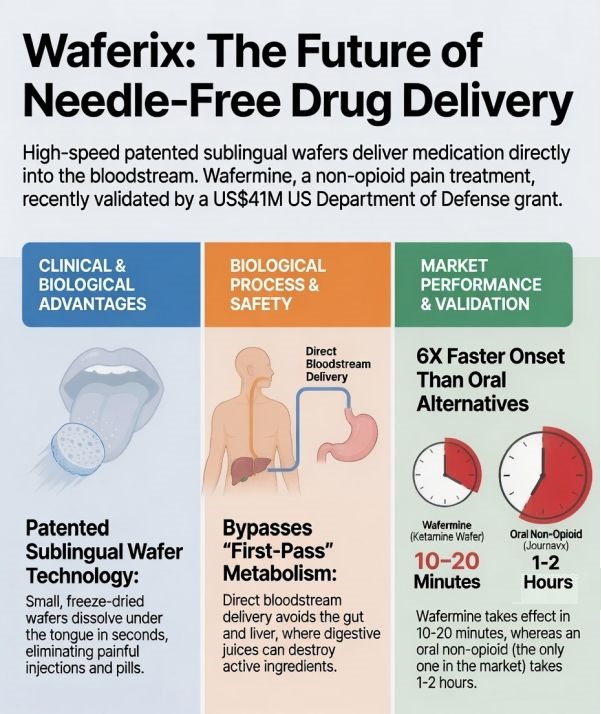
• EUA offers an early proof-point ahead of Phase 3 – The US Secretary of War's military emergency determination on 15 Jul 2026 and the declaration by the Secretary of Health and Human Services (HHS) on 31 Aug 2026 (published on 3 Sep 2026) created the legal pathway for FDA to consider emergency use of drugs for moderate-to-severe acute pain in military casualties.
Wafermine is not named, but it is the programme DoD is funding, and iX could potentially complete its EUA filing in 4Q26, with approval potentially in 1Q27 and initial DoD supply potentially from 2Q27.
Before Phase 3 data, an EUA would show that FDA accepts the chemistry, manufacturing and controls (CMC) package, that iX can manufacture at commercial scale in the US and that DoD demand is real.
The direct financial contribution is likely to be modest at first. Management indicates potential EUA supply of about USD6.6–13.2m over the three-year contract. However, we think EUA approval would strengthen confidence in the platform and in Wafermine's path to full approval.
• Phase 3 design risk is likely low, with commercial value tied to label and partner – Wafermine's Phase 2b study in 125 post-surgical patients delivered a pooled effect size of 0.65 at the 75mg dose (p<0.01) across bunionectomy and abdominoplasty models, and the Phase 3 programme is expected to use the same models and primary endpoint, with studies potentially starting in 3Q27 and topline data potentially in 2Q28.
Repeating a successful design reduces protocol risk, and the Jan 2025 FDA approval of Vertex's Journavx (suzetrigine), whose pivotal trials used the same two surgical models, sets a recent precedent for a non-opioid on this endpoint.
Beyond approval, commercial value depends on how Wafermine is positioned.
Racemic ketamine is generic, a US Schedule III controlled substance, and its dissociative effects could invite prescribing restrictions in outpatient settings.
A favourable label and a well-capitalised partner would therefore be key to unlocking Wafermine's full value.
| US compounding offers a capital-light growth option |
iX is consolidating its compounding assets and nutraceuticals into Ligo Pharma, under a partnership framework with GLD Partners, LP and its wholly owned subsidiary Orion Specialty Labs, an FDA-registered 503B outsourcing facility in Nevada.  Eddy Lee, Chairman and CEO, iX Biopharma.The 503B route does allow sales to hospitals, clinics and 503A pharmacies without new clinical trials, and a pharmaceutical-grade freeze-dried wafer is differentiated in a segment dominated by basic reformulation.
However, a 503B facility may compound from a bulk drug substance only where FDA has listed that substance for clinical need or the drug is in shortage, and FDA's ongoing review of which peptides may be compounded shows the perimeter is still being redrawn.
We therefore take a measured approach, assuming a subset of the pipeline launches at the outset, with further products offering upside as eligibility is clarified.
• Balance sheet repaired, with further funding likely in FY28E – Placements of 67m shares at SGD0.10 (31 Oct 2025) and 75.8m shares at SGD0.198 (24 Feb 2026), together with warrant exercises, lifted cash and cash equivalents to SGD14.7m at 30 Jun 2026 from SGD0.9m a year earlier, and net assets to SGD15.4m from SGD0.4m.
The share count rose to about 1.07b in FY26 from 888m over the year.
We forecast operating cash outflow of SGD12.0m in FY27E as working capital builds ahead of DoD and compounding revenue, so cash is likely to fall to about SGD5.0m by end-FY27E.
We assume the shortfall is bridged by short-term borrowings, which could potentially rise to SGD18.4m by end-FY28E.
With Phase 3 externally funded, any further funding need is likely to be driven by Ligo Pharma and corporate overheads rather than by Wafermine.
• Initiate coverage with a BUY rating and FV estimate of SGD0.92 Our FV is most sensitive to the Phase 3 outcome and deal terms. This implies upside of about 111% from the last close of SGD0.435. |
 See also: iX BIOPHARMA: KGI Initiates Coverage With S$1.17 Target Price. Why Bullish? |


