|
Excerpts from DBS Group Research report
Analyst: Ho Pei Hwa
• Higher-priced contracts offer further margin upside from the record 37.1% in 1H26
• Positive order momentum in 3Q should lift FY26 wins above the USD4.5bn target and new record orderbook above USD25bn, providing visibility through 2030
|
|||||
| Investment Overview |
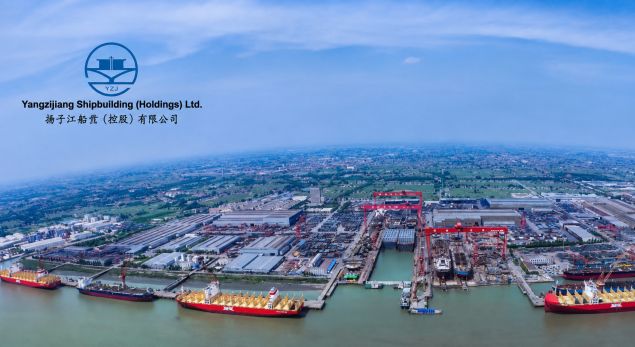
Best-in-class private shipbuilder with a widening competitive moat. Yangzijiang Shipbuilding (YZJ), is China’s second-largest private shipbuilder and one of its most efficient and profitable, supported by superior execution, disciplined cost control and an estimated ≥5ppt cost advantage over Chinese and Korean peers.
Its proven capabilities in large dual-fuel containerships and gas carriers reinforce its competitive position, while the delivery and successful operation of its first LNG carrier should establish an important track record in a technically demanding segment.
Higher contract prices offer further room for margin expansion. Shipbuilding gross margin reached a record 37.1% in 1H26 as higher-priced vessels secured during the upcycle progressed through construction.
We see further upside as a larger proportion of these contracts moves into revenue recognition, supported by favourable contract pricing, yard optimisation and disciplined cost control.
The ramp-up of Hongyuan provides an additional volume lever and should lift total shipbuilding capacity by c.20% by end-2026.
Multiple capacity levers extend the growth runway beyond 2029. The USD22.4bn orderbook provides delivery visibility through 2029, while Hongyuan (+20% capacity) supports nearterm volume growth and the potential development of the Runze yard (+30% capacity) could extend growth beyond 2029.
The Hongda repair yard adds a complementary, shorter-cycle revenue stream and positions Yangzijiang to capture growing demand for vessel repairs, retrofits and decarbonisation-related upgrades.
Together, these initiatives should sustain earnings growth beyond the delivery of the existing orderbook.
Reiterate BUY; TP raised to SGD6.60 (prev SGD5.60), based on 3x FY27F P/BV (prev 2.6x P/Bv), implying 11.5x FY27PE.
|
 See also: YANGZIJIANG SHIPBUILDING: This Company Has Mega Mix of Margins, Orders (US$22 Billion), Dividends |


