|
Singapore investors could soon get another semiconductor-related stock to consider.
The number of placement shares and placement price have yet to be filled in. |

| What does Metasurface actually do? |
Metasurface listed on Hong Kong's GEM board on 2 July 2024 at HK$2.42 a share, issuing 27 million shares.
The stock has recently traded around HK$3.50–HK$3.60.
That gives Singapore investors something unusual: a ready-made market valuation against which to judge the SGX placement price.
The business is quite straightforward.
Metasurface is a precision component engineering company, specialising mainly in precision machining and precision welding. Its components go predominantly into semiconductor manufacturing equipment. 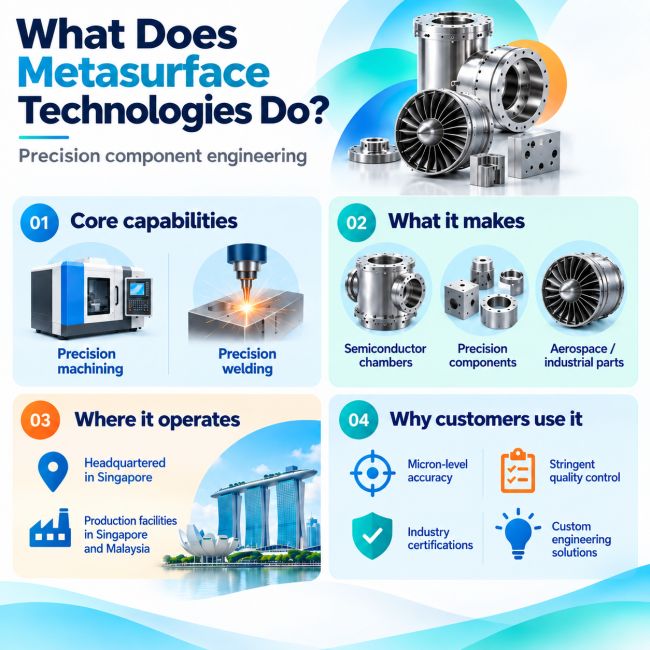
The work can be extremely demanding. Metasurface says it can manufacture certain components to ±5 microns precision, which helps explain why customers need suppliers to be qualified and certified.
Semiconductors have also become increasingly dominant: they accounted for 95.3% of group revenue in 1H2026, up from 92.2% in FY2025.
| Revenue is growing |
The underlying earnings trajectory is considerably better than the headline 58% decline in reported profit suggests.
|
Period |
Revenue (S$m) |
YoY change |
PATMI |
YoY change |
|
FY2023 |
38.8 |
— |
4.6* |
— |
|
FY2024 |
37.7 |
-2.7% |
3.2 |
-30.7% |
|
FY2025 |
47.6 |
+26.2% |
10.1 |
+216% |
|
1H2025 |
24.8 |
— |
8.8 |
— |
|
1H2026 |
27.0 |
+8.9% |
3.7 |
-58% |
*FY2023 net profit included S$2.14 million from discontinued operations.
Reported profit fell 58% to S$3.7 million in 1H2026, but the comparison is distorted by several unusual items.
Most notably, 1H2025 contained a S$6.4 million remeasurement gain related to MetaOptics, while 1H2026 included S$916,000 of SGX-listing expenses.
Share-based payments and finance costs also differed substantially between the periods.
The underlying business therefore performed considerably better than the headline 58% profit decline suggests, although core earnings growth appears modest.
| The order book is the exciting part |
The standout number in the offer document is the S$46.3 million order book at 30 June 2026, expected to be fulfilled by around March 2027.
That is almost equivalent to an entire year of FY2025 revenue.
There are signs of capacity pressure too.
Precision-welding utilisation at its Singapore factory reached an estimated 114.1% in 1H2026, reflecting additional manpower and hours used to meet demand.
Management says it expects overall revenue to continue growing, helped by semiconductor and precision-engineering demand.
Two negatives: Gross margin slipped from 42.0% to 38.1% in 1H2026, while operating cash flow plunged from S$5.1 million to just S$0.7 million, largely because inventories and receivables increased sharply.
Customer concentration is also high: major customers accounted for 85% of 1H2026 sales.
Using HK$3.60 as a reference, the Hong Kong shares are worth roughly S$0.59 each.
|
 → See earlier story:METASURFACE TECHNOLOGIES: This S'pore company rallies on 1H earnings, broker upgrade & associate MetaOptics' spectacular debut on SGX
