|
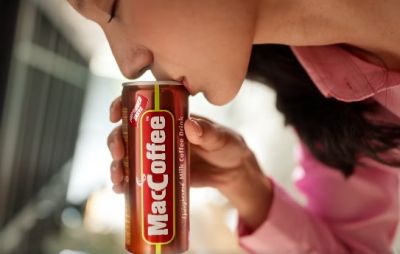
Food Empire’s shares recovered yesterday (22 Sept), closing 3.2% higher at S$1.95 after Monday’s 10% plunge to S$1.89. The sell-off followed concerns about Russia placing Nestlé’s local assets under temporary administration. UOB Kay Hian’s John Cheong and Tang Kai Jie consider the correction excessive. Their report this morning (23 Sept) retains BUY and a S$3.49 target, with earnings forecasts unchanged.
|
| Could short sellers fuel a rebound? |
The most interesting new information in the UOBKH report is the short-interest figure, rather than evidence that Food Empire’s Russian assets are protected.
The report says 10.6 million shares were short as at 11 Sept, roughly 5% of free float, citing MAS data.
A trading-week old, the snapshot predates Monday’s sell-off but one may speculate that short-sellers were active on Monday.
Short sellers typically buy back shares when closing their positions, potentially providing support for a rebound. That is a possible catalyst — not evidence that short covering is already under way.
Acting in the opposite direction, Food Empire bought 500,000 shares on 21 Sept at an average S$1.9035 each, committing approximately S$953,202 including expenses.
The next day, it bought 250,000 shares (S$1.9386 average), following on its verbal reassurance:
"FEH is headquartered in Singapore. The Group has operated in Russia for over 30 years, and it has manufactured locally in Russia since 2006. As at the date of this announcement, FEH's Russian operations continue in the ordinary course of business."
| The earnings story continues |
UOBKH also highlights Robusta at US$3,780 per tonne, 35% below its peak, alongside expected second-half contributions from Kazakhstan’s new coffee-mix facility and expanded Malaysian snack production.
Lower input costs could improve Food Empire's margins and profitability.
Extra production capacity offers a reason to expect higher revenue in the future.
There could also be competitive opportunities.
CGS International previously suggested that disruption to Nestlé’s supplies might allow Food Empire to gain market share.
Here are the analysts' recommendations:
|
Broker |
Report date |
Rating |
Target price |
|
UOBKH |
21 Sept 2026 |
Buy |
$3.49 |
|
CGS Int’l |
23 Sept 2026 |
Add |
$3.33 |
|
KGI Securities |
19 Aug 2026 |
Outperform |
$3.186 |
|
DBS |
17 Aug 2026 |
Buy |
$3.05 |
|
Maybank |
13 Aug 2026 |
Buy |
$3.29 |
|
UBS |
19 Aug 2026 |
Buy |
$3.00 |
|
 For earlier story, see: FOOD EMPIRE: Nestlé’s Russia Troubles Cast a Shadow. But CGS Sticks With $3.33 Target |


