• Tesla stock has surged 60+% in just the past 4 weeks, catalysed by Donald Trump winning the US presidential election. Tesla is widely seen as being well-positioned to benefit as Tesla's Elon Musk has been a staunch supporter of Trump. • At its core, Tesla has several emerging business segments that are on track to be hugely profitable. These include robotaxis and humanoid robots. • Over in China, EV rivals are furiously keeping up with Tesla. While BYD and Xiaomi are developing autonomous driving, they have not explicitly talked about robotaxis as a product offering. • In that respect, HK-listed XPeng (market cap: HK$86 billion) stands out as it is applying its autonomous driving capability to robotaxis that it will roll out as soon as 2026. • Unlike Tesla, XPeng has yet to turn profitable, so it's still a somewhat speculative stock. But with the vast market potential of robotaxis -- and EVs --XPeng stock could provide a good return. Well, DBS Research has a target price with nearly 40% upside. Read excerpts of its report below .... |
Excerpts from DBS Research report
Analysts: Rachel Miu & Raphael Tse
| AI propelling sales growth and margin expansion |
| Investment Thesis Strength in intelligent driving capability and EREV venture solidify medium term growth. XPeng Inc., a leading player in the autonomous driving (AD) industry, is capitalising on a strong sales backlog for its P7+ and MONA M03 models, along with four new models set for launch in 2025 (including an extended range electric vehicle [EREV] model). This leads us to raise our sales volume growth estimates to 65%/25% y/y to about 308k/385k units for FY25F/26F. The expansion into the EREV market with its Kunpeng Super Electric System (enabling seamless switching between pure electric and range-extended driving) is set to accelerate future growth. |
Additional growth potential driven by self-developed AI chip and potential launch of robotaxi by 2026.
|
XPeng |
|
|
Share price: |
Target: |
XPeng has developed an AI chip (Turing) with performance equivalent to three Nvidia Orin X chips, according to reports.
The breakthrough will enable the company to deploy L3+ AD capabilities by end-2025 and enter the robotaxi industry by 2026 with its new “Ultra” models.
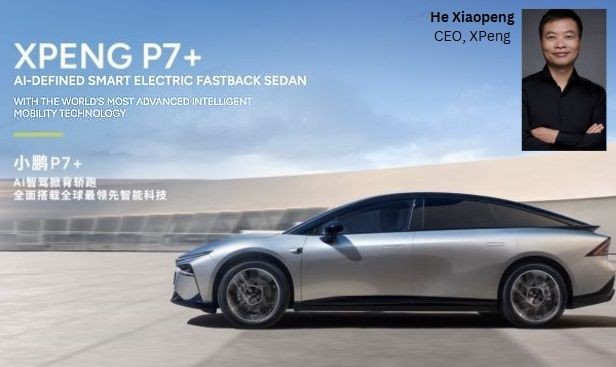
This underscores XPeng’s strong edge in automotive AI, building on the success of its first AI-enabled model P7+, which utilised visual-based solutions to support autonomous driving.
Margin outlook becoming more favourable.
Enhancing profit margins is crucial to lifting the company’s valuation.
Vehicle margins have been recovering from a negative 8.6% in 2Q23 to positive 8.6% in 3Q24 (+2.2ppt q/q), and is likely to reach c.10% in 4Q24, due to an improving sales, cost reductions, and higher overseas contributions (15% in 3Q24).
All in, we expect blended margin to hit c.17.3% in FY26, driven by scale benefits, new models, and a steady increase in contributions from its collaboration with Volkswagen.
| Maintain BUY; lift TPs to HKD67.0/USD17.0 (prev. HKD60/USD15). We lift our FY25/FY26F revenue estimates by 4%/3% to factor in the upward volume sales revisions. TPs were raised to HKD67.0/USD17.0, pegged to 1.7x FY25F P/S on strong model cycle (previously 1.6x). Reiterate BUY on improving sales and margins, which could help the company achieve operating breakeven in 4Q25. Key Risks Lacklustre user experience in vision-based solutions, and weak economic activity lowering EV sales. |
Full report here.